Alphabet's cloud business more than doubled its revenue, and the stock still had its worst day since its 2004 listing. The AI trade has moved from a story about demand to a story about who can pay for the build-out.
Alphabet's cloud business more than doubled its revenue, and the stock still had its worst day since its 2004 listing. The AI trade has moved from a story about demand to a story about who can pay for the build-out.
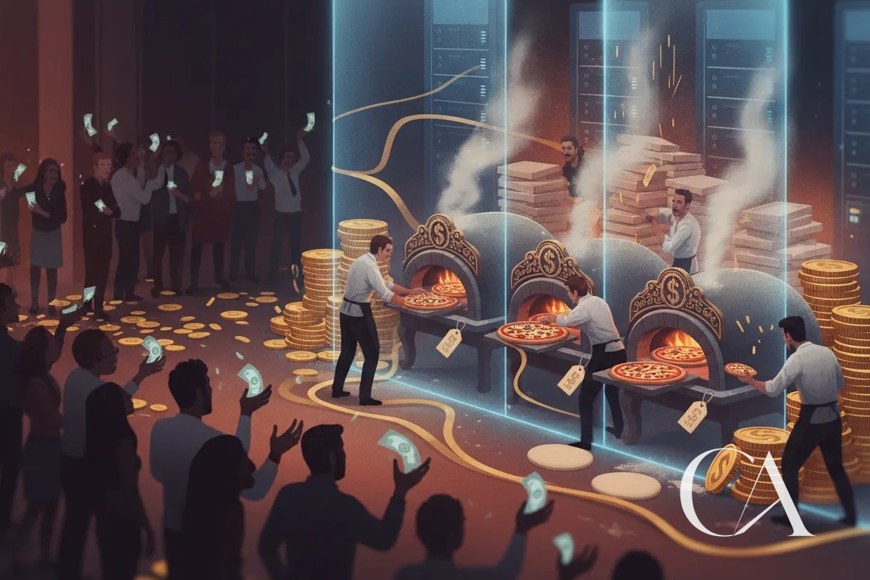
Picture a restaurant so popular that the line wraps around the block and sales double year over year. Now add one fatal flaw: to keep up with demand, the owner has to buy a new $10,000 commercial oven every time a customer orders a pizza. Sales are booming, and the business is going broke buying ovens. That is the paradox the stock market priced this week.
Below, I break down what Anthropic's IPO filing reveals about real AI demand, why the four largest cloud spenders now spend more than they generate, how they are funding the gap, and where investor capital went instead.
At a Glance
$16.3 billion: Anthropic revenue in the first half of 2026, up from $1.16 billion a year earlier
$201.9 billion vs. $175.5 billion: third-quarter capital spending vs. operating cash flow at Alphabet, Microsoft, Amazon and Meta
−12.6%: Alphabet Class A shares on October 29, the worst session since its 2004 listing
Up to $95 billion: Meta's planned equity raise, the largest in its history
5.8 points: the equal-weight S&P 500's October lead over the cap-weighted index, the widest since April 2009
1.The growth paradox
Alphabet reported third-quarter revenue of $127.6 billion, up 25%, and Google Cloud revenue of $30.7 billion, up 103%. The market's answer was the steepest one-day decline in the stock's history as a public company: Class A shares fell 12.6% on October 29, erasing roughly $500 billion of market value.
The reason sat in the cash flow statement. Alphabet spent $51.4 billion on property and equipment in the quarter, more than the $42.3 billion its operations generated, which left free cash flow at negative $9.1 billion. Triple-digit growth was not enough, because the cost of delivering it is rising faster than the revenue it produces.
That is the shift this week's newsletter is about. For two years the AI trade was a demand story. It is now a funding story: the question is no longer whether customers want AI, but who can afford to build the physical infrastructure that serves them.
2.Inside Anthropic's S-1: the demand is real
Anthropic made its IPO prospectus public on October 26, 2026, and it offers the clearest view yet of enterprise AI demand. Revenue for the first six months of 2026 reached $16.3 billion, up from $1.16 billion in the same period of 2025. That is an increase of roughly 1,300%, or about 14 times, in a single year.
This is not casual chatbot use. The filing reports more than 11,900 customers generating at least $100,000 of revenue on a trailing twelve-month basis, and roughly 250 generating at least $10 million. Large companies are building these models into their daily workflows.
Figure 1. Anthropic, first half of each year ($ billions)
Source: Anthropic, PBC Form S-1, filed October 26, 2026, as reported by TNW and Leverage Shares.
3.The $80.7 billion loss that is mostly not cash
Headlines focused on the first-half net loss of $80.7 billion. Set beside $16.3 billion of revenue, that number looks alarming. Most of it, however, is an accounting entry.
Anthropic financed part of its growth with convertible notes and similar instruments: debt that can later convert into shares. As the company's valuation rose, the shares owed to those investors became more valuable, and accounting rules require the company to record that increase as a cost. The filing books a $72.4 billion non-cash charge for the change in fair value of these instruments.
The operating figures tell a different story. The operating loss was $693 million, down from $2.14 billion a year earlier: a cut of roughly two-thirds while revenue grew about fourteenfold. In the second quarter alone, Anthropic posted its first operating profit, $974 million. The company has raised $141.1 billion since its founding and held $112.4 billion in cash on June 30, plus $19.3 billion in short-term investments.
The lease analogy
Signing a 10-year lease on a $100,000 office does not mean you lost $100,000 this week. Much of the commentary on Anthropic's filing confused a paper revaluation, or a total future commitment, with day-to-day cash burn.
4.The real pressure point: renting the compute
The footnote that matters most is not the net loss. It is the size of Anthropic's compute commitments. The S-1 shows between $542 billion and $567 billion of future spending committed to compute and infrastructure. The largest counterparties are Broadcom at about $161.2 billion, Google at $114.5 billion and Amazon at $110 billion, with up to $84.5 billion committed to SpaceX and $44.9 billion to Microsoft.
Anthropic builds frontier models, but it does not own most of the physical infrastructure needed to train and run them. Training a frontier model means linking tens of thousands of specialized processors inside large data centers that run near full capacity for months. Locking up that capacity early is expensive, and it also keeps the capacity away from competitors.
Figure 2. Anthropic compute commitments by counterparty ($ billions)
Source: Anthropic Form S-1, as summarized by Benzinga and OfficeChai. SpaceX figure is a maximum. Total commitments: $542 billion to $567 billion.
5.The capex accountability trade
If Anthropic is committing hundreds of billions of dollars to rent compute, the companies that own the compute should be flush with cash. This week showed the opposite. Their money is going straight into concrete, steel and silicon, and Wall Street is now demanding accountability for that spending.
Alphabet, Microsoft, Amazon and Meta spent a combined $201.9 billion on property and equipment in the third quarter. In the same quarter, the four generated $175.5 billion of operating cash flow. The difference is a $26.4 billion shortfall.
A year earlier, the same four companies had more than $60 billion of free cash flow left over after paying for their infrastructure. In twelve months, they have moved from a large surplus to a combined cash deficit.
Figure 3. Third quarter of 2026: capital spending vs. operating cash flow ($ billions)
Source: company filings and releases for the quarter ended September 30, 2026 (Microsoft fiscal Q1 2027). Capex = cash purchases of property and equipment. Meta operating cash flow derived from its reported free cash flow.
Figure 4. Combined free cash flow of the four hyperscalers, third quarter ($ billions)
Source: our arithmetic from company filings (operating cash flow minus cash purchases of property and equipment).
The spending goes to land, cooling systems, dedicated power substations and hundreds of thousands of accelerator chips. Power density is a large part of the bill. A traditional data center rack draws roughly 10 to 15 kilowatts. A flagship AI rack draws about 100 to 120 kilowatts, which forces liquid cooling and a much larger electrical system. In practice, entire buildings have to be redesigned around the hardware.
Figure 5. Power drawn per rack (kilowatts)
Source: industry estimates from Introl and Chatsworth Products; ranges vary by hardware configuration.
6.Funding the gap means dilution
When capital spending runs ahead of operating cash, the difference has to come from somewhere. Alphabet sold $12.4 billion of new Class A and Class C shares through its at-the-market program in the third quarter, part of the $84.75 billion equity raise it announced in June. It bought back none of its own stock in the quarter, against $11.5 billion a year earlier.
Meta is going further. On October 26 it announced plans to raise up to $95 billion, the largest equity raise in its history: about $35 billion of underwritten Class A common stock and mandatory convertible preferred stock, plus an at-the-market program of up to $60 billion in new non-voting Class C shares, expected to begin once those shares start trading.
Why at-the-market programs worry shareholders
An at-the-market program lets a company sell new shares into the open market gradually, whenever it chooses. Investors read it as a standing supply of stock: every rally becomes an opportunity for the company to sell, which can cap the share price and steadily dilute existing owners.
Dilution is simple arithmetic. Each new share makes the ownership pie larger and each existing slice smaller, so current holders own a smaller share of future profits every time stock is issued to buy more servers.
7.The bull case, and the timeline problem
There is a serious counterargument. Amazon spent years in the late 1990s and 2000s building fulfillment infrastructure at a loss to dominate e-commerce, and patient shareholders were rewarded. Valuations also look less stretched than the headlines suggest: Nvidia's forward price-to-earnings ratio (the price paid today for a dollar of next year's expected earnings) fell during 2026 to its lowest levels in years, because earnings estimates have climbed faster than the share price.
The market's answer is about duration. Investors are starting to treat the AI build-out as a 20- to 30-year infrastructure project rather than a two-year spending wave. Funding a structural shortfall for that long requires repeated share issuance, and shareholders are discounting that dilution today.
“It does not matter if your cloud division doubles its revenue if you are diluting your shareholders to pay for the servers.”
The new test for AI winners
8.Microsoft: the self-funded exception
Microsoft was the one hyperscaler the market rewarded this week. Its operating cash flow for the September quarter was $58.0 billion, comfortably above $39.4 billion of cash capital spending, which left $18.6 billion of free cash flow. Its shares rose after the report.
Microsoft is paying for future infrastructure with the profits it generates today, without turning to the equity market. Chief financial officer Amy Hood said the company expects to remain free cash flow positive in fiscal 2027. That is the profile investors now reward: self-funded growth over externally financed expansion.
9.Neoclouds: when GPUs are the collateral
If the largest and most profitable companies are issuing stock to fund AI, the pressure on smaller players is greater. Neoclouds such as CoreWeave and Nebius buy large fleets of GPUs and rent them out by the hour for AI workloads. CoreWeave shares fell almost 30% in October through October 22, and Nebius fell 36% in the 17 days to October 22, as financing worries spread through the group.
The problem is the collateral. A logistics company that borrows against a warehouse offers an asset that holds value for decades. A neocloud borrows against chips that age quickly. Hourly H100 rental rates fell 60% to 70% from their 2024 peak, and one appraiser values an H100 at 27% to 39% of its original list price in 2026, falling to 5% to 7% by 2028. Lenders are reluctant to advance billions of dollars against assets on that curve.
Without large non-AI revenue to support their borrowing, such as Microsoft's software franchise or Amazon's broad cloud business, neoclouds depend on credit markets that are becoming more expensive and more selective.
The end-to-end moat
The episode highlights a structural advantage. Only two players currently own both a leading consumer-facing AI model and the infrastructure to run it at scale: Google with Gemini and Meta with Muse. Anthropic and OpenAI, despite highly competitive models, rent much of their compute from companies that are also their competitors.
It is like running an airline whose biggest rival owns the airports and the fuel supply and leases you the planes: over time, the landlord controls your margins. Meanwhile, the cost of processing each AI token (the basic unit of text a model handles) keeps falling, while total usage grows so quickly that absolute spending on compute keeps rising. A wave of acquisitions, with model developers buying distressed capacity to own the stack from silicon to software, looks increasingly likely.
10.Where the money went: rotation, not evaporation
Capital did not disappear; it rotated. The Nasdaq Composite fell 5.3% in October, its worst month since March 2025, while the S&P 500 slipped 0.9%. The equal-weight S&P 500, which gives its smallest member the same weight as its largest, gained 4.9%. That 5.8-percentage-point lead over the cap-weighted index was the widest monthly margin since April 2009. In plain terms, most stocks rose while a handful of technology giants fell.
Figure 6. October 2026 index performance (%)
Source: Investing.com, The Motley Fool and Bespoke Investment Group (via Seeking Alpha); price returns.
The casualties were concentrated. Intel closed down 28.6% on October 30 after a weak fourth-quarter outlook, its worst session since 1974, as investors focused on a shrinking PC market while AI spending flows to chips Intel does not dominate. ServiceNow fell 26.9% on October 29, its worst day on record, and Reddit fell nearly 30% on October 30.
The beneficiaries were defensive. Eli Lilly rose 6.6% on October 29 to a record close of $1,373.70 after raising its 2026 revenue forecast. A pharmaceutical company has essentially no AI capex exposure: it will not need to borrow tens of billions of dollars to build a data center.
Figure 7. Single-session moves, October 29 to October 30, 2026 (%)
Source: Trefis and Yahoo Finance closing prices.
11.Rates and the flight to safety
The Federal Reserve held its target range at 3.75% to 4.00% on October 28, but the vote was 10 to 2, with Governor Lisa Cook and Cleveland Fed President Beth Hammack dissenting in favor of a quarter-point hike. Markets now price roughly a 75% to 85% chance of a December hike, within reported estimates of about 70% to 86%.
Fear of rate hikes normally pushes yields up. Instead, the 10-year Treasury yield fell below 5% on October 22, down from a peak of about 5.36% on October 7, while technology stocks fell. When bond yields and stocks fall together, the signal is not inflation fear. It is a flight to safety: investors are moving capital out of companies that must borrow at today's higher rates to fund AI capex, and into government bonds and defensive sectors such as health care.
Wild cards
Today's U.S. midterm elections and the geopolitical situation affecting oil prices could influence inflation and regulation over the coming months. We take no political side on either. Based on this week's data, the core market driver remains the funding of AI infrastructure.
12.What to watch from here
Capex vs. operating cash flow: which companies can fund their build-out internally, and which are turning to debt or equity markets.
Share count: at-the-market sales, convertible issuance and paused buybacks that dilute existing owners.
Compute commitments: contracted spending that must be paid regardless of usage, and who ultimately carries it.
Neocloud credit: borrowing costs, facility maturities and the resale value of the GPUs pledged as collateral.
Breadth and rates: whether the equal-weight lead persists, and whether the Fed hikes in December.
13.Conclusion: the builders take the risk, the users may take the reward
Enterprise demand for AI is historic, and it is real. The physical cost of meeting that demand is so large that it is breaking the free cash flow of the world's most powerful companies, and Wall Street has shifted its focus from raw growth to balance-sheet survival.
One question deserves a place on every investor's list. The build-out is happening regardless of this week's stock reaction; the concrete is being poured. If it leads to a glut of computing power within five years, the price to rent compute could fall until it behaves like a cheap utility. In that scenario, the biggest winners of the AI era may not be the hyperscalers financing today's data centers, but a generation of software companies that do not exist yet, building on cheap, abundant capacity. The original restaurant owner may go bankrupt building the world's best kitchen, while the next chef buys the fully equipped building at auction and makes a fortune.
IMPORTANT DISCLAIMER: This document is provided for informational and educational purposes only. It does not constitute investment, legal, tax, or other professional advice, and nothing herein should be construed as a recommendation, offer, or solicitation to buy or sell any security. Information is from sources believed reliable but not guaranteed; certain figures are estimates that may prove incorrect. Past performance is not indicative of future results, and all investments involve risk, including possible loss of principal. Conduct your own due diligence and consult a licensed professional before investing. Carlos Artiles accepts no liability for any loss arising from use of this material.
CARLOS ARTILES · Strategy. Growth. Life by Design.Informational use only, not investment advice
Comments (0)
No comments yet — be the first.